Saving for a down payment is one of the biggest hurdles for Canadians trying to buy their first home. So when a parent or family member offers to help with a gift, it feels like the hard part is over.
It’s not.
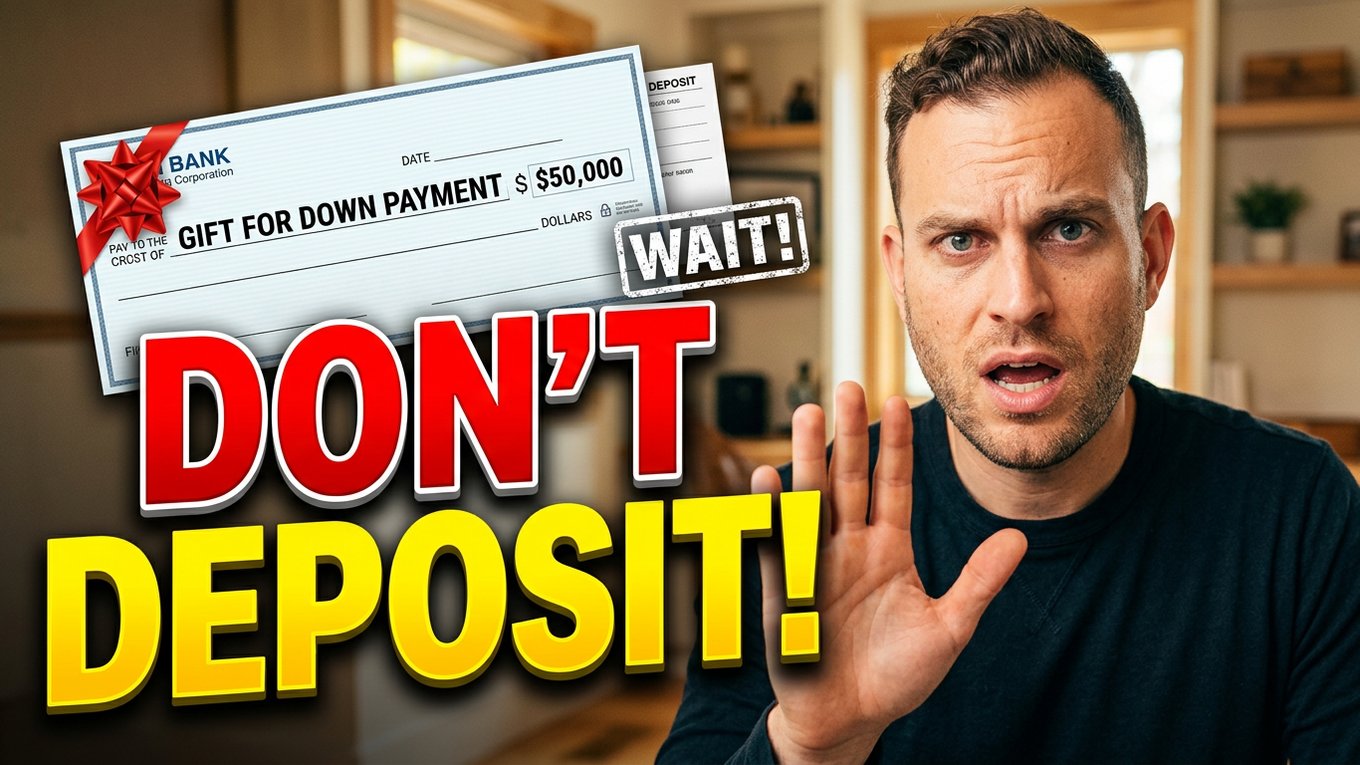
I’ve seen gifted down payments go sideways more times than I’d like to admit. Not because the gift itself was a problem, but because the paperwork was handled wrong, the timing was off, or someone tried to DIY a gift letter they found on Google.
Here’s what you actually need to know to make sure your gifted down payment doesn’t become the thing that tanks your mortgage approval.

What Counts as a Gifted Down Payment?
A gifted down payment is money from a family member that you don’t have to pay back. That’s the key piece. If there’s any expectation of repayment, it’s not a gift… it’s a loan. And lenders treat those very differently.
With a gift, the money doesn’t affect your debt ratios at all. With a borrowed down payment, that repayment obligation gets factored into what you can qualify for. I’ve watched people lose tens of thousands of dollars in purchasing power because their “gift” was actually structured as a loan.
Most lenders accept gifts from immediate family: parents, siblings, grandparents. Some will consider gifts from a spouse or extended family on a case-by-case basis, but don’t assume. Check with your broker first.
The Gift Letter Mistake I See All the Time
Here’s where most people trip up.
They hear “gift letter” and immediately start drafting something themselves. Maybe they find a template online, maybe they write something up in Word. They think they’re being proactive and getting ahead of the process.
Don’t do this.
The gift letter comes from the lender. Every lender has their own template with their own letterhead and their own specific requirements for what needs to be included. When you show up with a homemade gift letter, you’re creating extra work for everyone… and sometimes the lender will reject it outright because it doesn’t match their format.
What goes on the actual gift letter? It’s straightforward: the gift amount, the relationship between the giver and the buyer (e.g., “this is my daughter”), a statement confirming the gift is non-repayable, the date, and some basic personal details like the giver’s address.
Your broker will get you the right template once you have an approval. That’s part of the job.
Is There a Maximum Gift Amount?
There’s no hard cap on how much someone can gift you. Technically, your parents could gift you the entire purchase price and you wouldn’t need a mortgage at all.
But here’s the catch. Once the gift gets into larger amounts… say over $100,000… expect the lender to ask for additional documentation. They’ll want to see where the money came from. Bank statements showing the source of funds are standard. This isn’t personal. It’s anti-money laundering compliance, and every lender in Canada has to follow these rules.
Do You Pay Tax on the Gift?
This is a question for your accountant, not your mortgage broker. That said, in most cases I’ve seen, there are no tax implications for the person receiving the gift. The person giving the money has already been taxed on it.
But there are edge cases. Different family structures, different amounts, different provinces… it gets specific fast. Talk to an accountant before you assume you’re in the clear.
What About Gifts From Outside Canada?
This one gets complicated, and it really does depend on the country.
If the gift is coming from a sanctioned country, it’s going to be very difficult or outright impossible to use. For non-sanctioned countries, it’s usually possible, but expect a longer process. The lender will likely want additional documentation, and I’ve had cases where foreign bank statements needed to be fully translated by a certified translator before the lender would even look at them.
Every international gift scenario is case by case. Don’t wait until the last minute to bring this up with your broker. If you know money is coming from overseas, flag it early so there’s time to gather everything.
The Timing Matters More Than You Think
One thing people don’t realize: you need to get the funds transferred and documented before closing. This isn’t something you can sort out the day before you get the keys.
Work with your broker on the timeline. They’ll tell you when the money needs to move, how to document the transfer, and what the lender needs to see as proof. Getting this sequence wrong is one of the fastest ways to delay or derail a closing.
Ready to Use a Gifted Down Payment?
If your family is helping with your down payment, the best thing you can do is talk to a mortgage broker before anyone moves any money. I’ll walk you through exactly what documentation you need, connect you with the right lender, and make sure the gift doesn’t create any surprises down the road.